One move, two transactions − and a plan that keeps both on track.
If you plan to buy and sell a house simultaneously, it may feel like two transactions competing for your attention. You are weighing two prices, financing, contract dates, and the logistics of getting from one address to another.
The goal is not necessarily to make both closings happen on the same day. It is to choose a sequence that gives you enough financial and practical breathing room if a closing shifts or the right home takes longer to find.
For Fairfield County homeowners, that decision begins with two separate questions: How readily is your current home likely to sell, and how difficult will it be to secure the type of property you want next?
Table of Contents:
- Start with your financial position − not the home search
- Coordinating a home sale and purchase: Three approaches
- Consider Fairfield County’s micro-markets
- Your planning timeline
- Protecting both transactions with a backup plan
- How a Fairfield County Realtor keeps both transactions on track
- Plan your sale and next purchase together
Start with your financial position − not the home search
Before touring homes, determine how much of your next purchase depends on the equity in your current one. A realistic estimate should account for the likely sale price, remaining mortgage balance, repairs or preparation, agent compensation, attorney and closing expenses, Connecticut conveyance taxes, and moving costs.
Then speak with a lender about the scenarios you could comfortably manage. Can you qualify for the next mortgage before selling? Could you carry both homes for a limited period? Would bridge financing, a home equity line, or another source of funds be available and appropriate? These are questions for a qualified lender, and the answers should be clear before you commit to a purchase.
Personal flexibility matters, too. A household relocating for work may have a firm deadline, while someone downsizing locally may be able to wait for the right condominium or single-level home. The plan must fit both the numbers and the reason behind the move.
Read more: Selling your Fairfield County home during a major life transition
Coordinating a home sale and purchase: Three approaches
Two homes, three possible paths − and one sequence that fits your move.
There is no best sequence for every homeowner. Each approach shifts the pressure to a different part of the move.
Option 1: Sell your current home first.
Selling first confirms your net proceeds and removes the uncertainty of carrying two properties. You may then be able to make an offer without a home-sale contingency.
Potential advantages
- You know how much cash is available for the next purchase.
- You avoid overlapping mortgage payments, taxes, insurance, and maintenance.
- You can make decisions without wondering when the current home will sell.
Possible tradeoffs
- You may need temporary housing and storage.
- A short-term rental may be difficult to match with an uncertain search.
- You could feel pressure to compromise if your next home does not appear quickly.
An extended closing or negotiated post-closing occupancy may provide more time, but the buyer must agree and the terms must be documented.
Option 2: Buy your next home first.
Buying first gives you time to wait for a property that fits. It can also make preparing your current home easier because you are no longer living through photography, showings, and open houses.
Potential advantages
- You can search without an approaching move-out date.
- You can move once instead of using interim housing.
- Your former home may be easier to repair, stage, and show after it is vacant.
Possible tradeoffs
- You may carry two mortgages and two sets of ownership costs.
- Funds for the down payment may need to come from somewhere other than sale proceeds.
- A slower-than-expected sale can add financial and emotional pressure.
Financing should be approved for the actual two-home scenario – not an informal expectation that the current property will sell quickly.
Option 3: Buy and sell at approximately the same time.
Coordinating the transactions can reduce interim housing and overlapping expenses, but it creates the most interconnected timeline.
Potential advantages
- Sale proceeds can be directed toward the next purchase.
- The household may avoid a long temporary stay.
- The period of double ownership can be limited or eliminated.
Possible tradeoffs
- A delay in one transaction can affect the other.
- A home-sale contingency may make an offer less attractive to some sellers.
- Inspections, appraisals, financing, attorneys, movers, and two sets of negotiations must stay aligned.
The aim is a carefully negotiated sequence with enough room to absorb a change.
Consider Fairfield County’s micro-markets
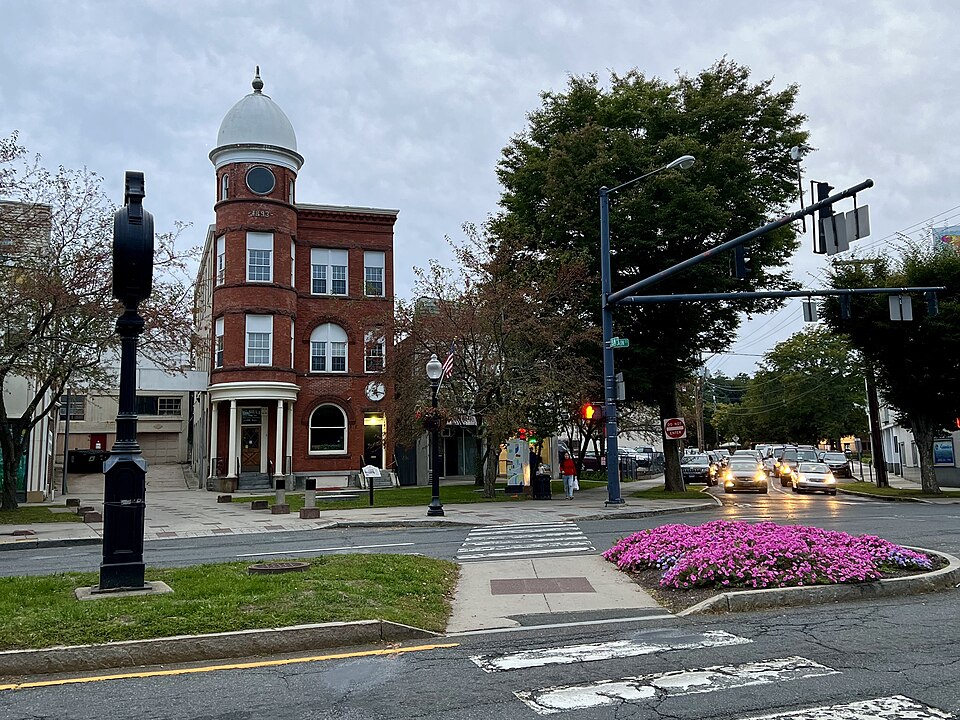
From coastal towns to inland centers like Danbury, Fairfield County is made up of distinctly different micro-markets.
Selling a home in Fairfield County requires a closer look than a county-wide headline provides. Demand may differ by town, neighborhood, price range, property type, condition, and even the features buyers expect at a particular price range.
A well-prepared home near the train in Westport, Fairfield, Norwalk, or Stamford may face a different buyer pool from a larger property with acreage in Easton or Weston. The search for a downtown condominium will not move like the search for a single-family home in Wilton, Trumbull, Danbury, New Canaan, or Darien. Your Fairfield County Realtor should compare recent activity for the property you own and the narrow segment you hope to enter next.
Local property details also tend to affect preparation time. Connecticut’s residential property condition report asks sellers about matters including flood and wetlands status, wells, septic systems, underground tanks, historic districts, association fees, permits, and prior water intrusion. Along the coast, buyers may request flood insurance history or an elevation certificate. For inland homes, well reports, septic service records, and oil-tank documentation may become important. Condo sellers in Stamford or Norwalk may need association documents and move-related requirements.
Gathering those records early keeps a missing document from becoming a last-minute problem.
Read more: What to know about selling a waterfront or near-water property in Westport, CT
Your planning timeline
Most homeowners benefit from starting three to six months before they hope to move. Begin six to twelve months ahead if the current home needs substantial work, the next property must meet narrow criteria, or new construction is involved.
| TIME FRAME | WHAT TO ADDRESS |
|---|---|
| 6–12 months before, if needed | Plan major repairs or deferred maintenance, consider the timing of new construction, and identify any property records that may take time to obtain. |
| 3–6 months before the move | Estimate net proceeds, meet with a lender, evaluate the current home’s likely market position, compare the three sequencing options, and set a working budget. |
| 1–3 months before listing | Complete priority repairs, declutter, prepare staging and photography, assemble disclosures and records, and choose a target launch date. |
| Before actively making offers | Secure pre-approval, confirm the source of the down payment and deposits, decide whether a contingency is necessary, and create a housing and storage backup plan. |
| Under contract | Track inspection, appraisal, financing, title, and attorney deadlines for both transactions; coordinate movers and confirm when possession will transfer. |
| Before closing | Verify funds, documents, utilities, insurance, final walkthroughs, keys, and the response plan if either closing moves. |
This is a framework rather than a fixed calendar. A spring listing, a waterfront property, a highly specific downsizing search, and a newly built home will not require identical lead times. A Fairfield County real estate agent should be able to refine the schedule around the property you are selling and the availability of the home you want next.
Protecting both transactions with a backup plan
When two contracts are connected, clarity matters more than optimism. Know which dates are firm, which can be negotiated, and what happens if an inspection issue, appraisal, mortgage approval, or title matter causes a delay.
Before signing, work through questions such as
- Where will the down payment and deposits come from at each stage?
- How long could you comfortably cover two homes?
- Could you use temporary housing if the sale closes first?
- Who will store your belongings if possession dates do not align?
- Which terms must be reviewed by your lender and Connecticut real estate attorney?
Your agent, lender, and attorney serve different roles. Keeping all three informed prevents a date negotiated in one transaction from creating a problem in the other.
How a Fairfield County Realtor keeps both transactions on track
Kim Vartuli and Michael Jabick can evaluate the current property’s position, help prioritize preparation, align the home search with the sale, and communicate with the professionals handling each deadline. That coordination is especially valuable when the proceeds from one closing must support the next purchase or when a specific move date leaves little room for error.
Plan your sale and next purchase together
Buying and selling at the same time becomes far more manageable when both transactions are guided by one clear strategy from the outset.
If you are looking to buy and sell a house simultaneously within or beyond Fairfield County, Kim Vartuli and Michael Jabick will help you evaluate your home’s market position, weigh your options, and build a plan around your timing and next-home priorities. Call 475.422.6961 or send an email to start the conversation.